01
A connected customer view
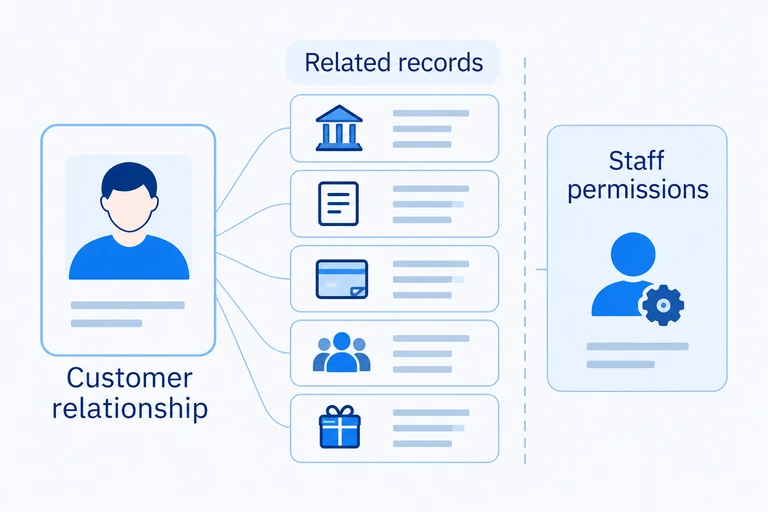
Bring profiles, accounts, transactions, contacts and benefits into the customer relationship view, subject to staff permissions.
Core banking for retail and savings banks serving individuals and sole proprietors.
Built on BX-CBP, the suite connects customer and transaction records across the bank’s retail operations. Customer Mobile App and Internet Banking are optional, allowing the bank to retain its existing channels.
Bring profiles, accounts, transactions, contacts and benefits into the customer relationship view, subject to staff permissions.
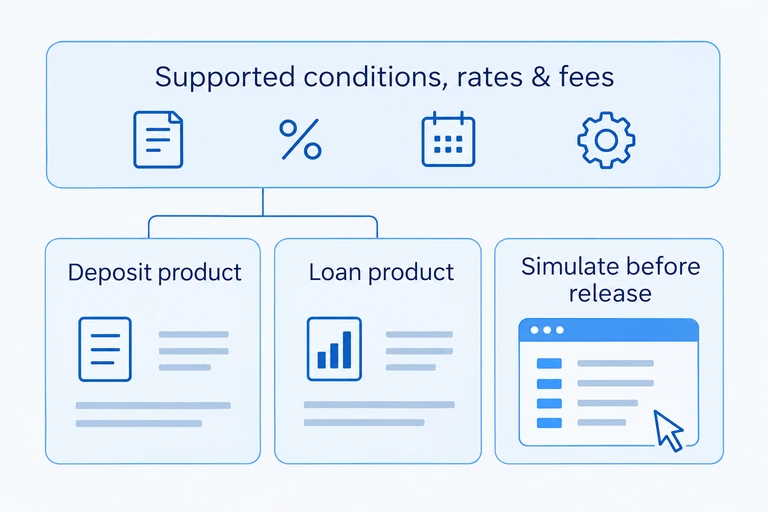
Define supported conditions, rates and fees in BX-PF and simulate changes before release.
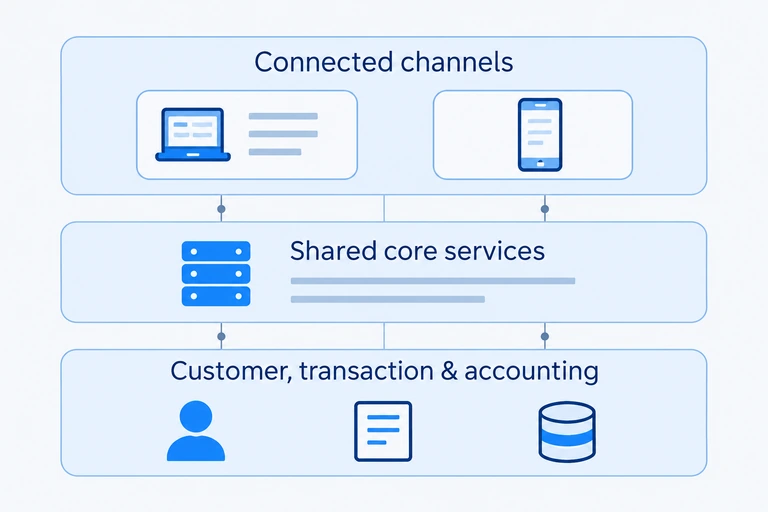
Use common customer, transaction and accounting services across the connected channels in your implementation.
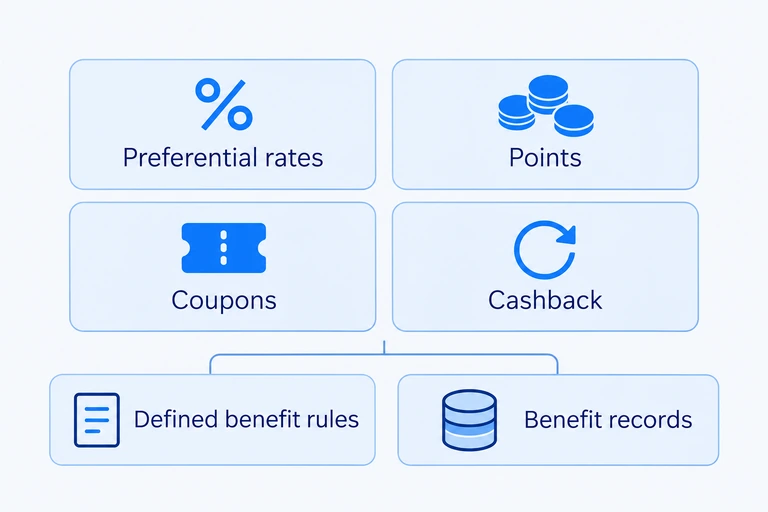
Manage preferential rates, points, coupons and cashback through defined benefit rules and records.
Function availability, interfaces and implementation scope are confirmed for the selected product version and institution. External services, local network connections and additional development are agreed separately.
Onboards individuals, sole proprietors, corporations, corporate entities, associations and correspondent banks, each with its required identification and documents.
One record shows a customer’s deposit, loan and FX balances, transactions, contacts and benefits on one screen.
Create, change, query, verify and terminate customer records through the same services from any channel.
Classifies customers by segment and holds a rating that pricing, limits and approval rules can reference.
Real-name verification and KYC at onboarding and on change, with an AML risk rating driving transaction restrictions and approvals.
Contact points are routed per service with change history, so notifications reach the address the customer chose.
Records the consents and authorisations a customer has given and applies them when data is used or shared.
One party holds Customer, Business Partner and Employee roles at once without duplicate records.
Blocks onboarding or contact for listed parties, with the reason and period recorded.
Staff see the customer fields and actions their role permits.
Opens, closes and terminates accounts early, applying the product’s early-termination interest and fee rules.
Posts deposits and withdrawals, handles counter cash, and pays interest on the product’s schedule.
Maintains attributes, transfers accounts between branches, sets inactive accounts dormant, and applies holds and freezes.
Runs time deposits, demand accounts and installment savings on the same services, with conditions held in the product.
Accrues interest daily, simulates it before a transaction, and composes the rate from a base plus preferential components.
Keeps available, actual and frozen balances separately, so holds and pending items never alter the ledger balance.
Issues deposit certificates, balance certificates, withholding-tax certificates and account statements.
Processes maturities and rolls over time deposits automatically under the account’s instruction.
Application, approval, disbursement, repayment and closure run on one loan record.
Property-secured lending with the collateral recorded against the loan.
Loans secured by collateral or by a pledged deposit certificate held at the bank. Collateral management is optional.
Loans supported by a third-party guarantee, with the guarantee recorded and tracked.
Disbursements, repayments, interest and fees post to accounting under journal-entry rules.
Card services depend on integration with external card management and issuing systems.
Connect core accounts and transactions to the bank’s external card management system through agreed interfaces.
Connect with the bank’s external issuing system for the agreed card-service workflows.
Support immediate, standing-order and scheduled transfers, with external interfaces and batch-linked processing defined for the implementation.
Execute scheduled transfers and standing orders through configured processing, including Center-Cut services where used. Timing and external interfaces are defined for the implementation.
Issues virtual account numbers per purpose, such as a collection or merchant, routing funds to the underlying account.
Customers set their own limits by channel and transfer type within the bank’s ceilings.
Provide transaction notifications through the agreed channels.
Post payment transactions to accounting under the applicable journal-entry and processing rules.
Determines and grants rate discounts, points, coupons, cashback and gifts under configured conditions.
Maintain benefit records under configured rules.
Customers add, remove, edit and query the candidate benefits offered to them.
Coupons from partners and suppliers are applied, redeemed and tracked through partner integration.
Preferential rates by balance tier, taking the maximum of the tiers a customer qualifies for.
Business staff launch and maintain products in the Configurator within supported configuration.
Rates, fees and conditions are configured per product and simulated before launch, independent of any account.
Release supported product definitions to agreed channels, with changes tracked and validated before release.
The same product is classified from risk, compliance, seller, buyer and finance views.
Maintain a product catalogue for the agreed comparison and management scope. AI-assisted entry is included only where supported in the selected product version.
Fees are managed in one place and simulated for what-if cases before a change goes live.
Transactions post in real time; items awaiting a later event post on a deferred basis.
A multi-entity, multi-level chart of accounts with parent-child aggregation.
Rules on product, amount type and account generate journal entries, within the supported posting model.
Authorised staff post manual entries; financial statements are produced from the ledger.
Reconciles the business ledger, off-balance items and the general ledger and reports differences.
Each settlement step is validated, its status tracked, and a failed step can be re-executed.
Records off-balance transactions and clears positions between branches.
Parks unmatched items in suspense accounts and tracks them to clearance.
Opens the business day, validates outstanding items before close, and closes the day.
Support cash, general ledger, journal, manual entry, balance verification, internal accounts and inter-branch accounts within the agreed accounting scope.
Support maker-checker approval through configured approval levels and rules.
Asynchronous tasks are monitored, rejection reasons tracked, and rejected items resubmitted.
Generates statements, contracts and certificates, and records inbound documents.
Generate account, contract and document numbers through configured numbering rules.
Use business-day and holiday calendars for configured value dates, maturities and processing schedules.
Restrictions by Actor, Customer or Contract, applied per channel.
Support notification content, multiple languages and shared common codes within the agreed configuration.
Manage organisation units, employees and role-based permissions.
Agency servicing is included. Enable account opening, deposits and withdrawals through agent banking, with an agent app available. Customer Mobile App and Internet Banking are available as options, and the suite can also connect to the bank’s existing channels.
A next-generation core for savings banking
Bankware delivered a next-generation core under the former BX-RBS name using BX-CBP, BX-PF and related platforms.
Retail Bank Suite
Case material references the Retail Bank Suite offering at Woori Financial Savings Bank.
Tell us about your deposit and lending products, customer service channels, benefit programmes and existing systems. We can help define the relevant core and integration scope.